GEO for Financial Services: A Sector-by-Sector US Playbook
When Americans ask AI about savings, loans or brokers, which sources get cited, and how does a bank, lender or fintech earn a place in the answer?
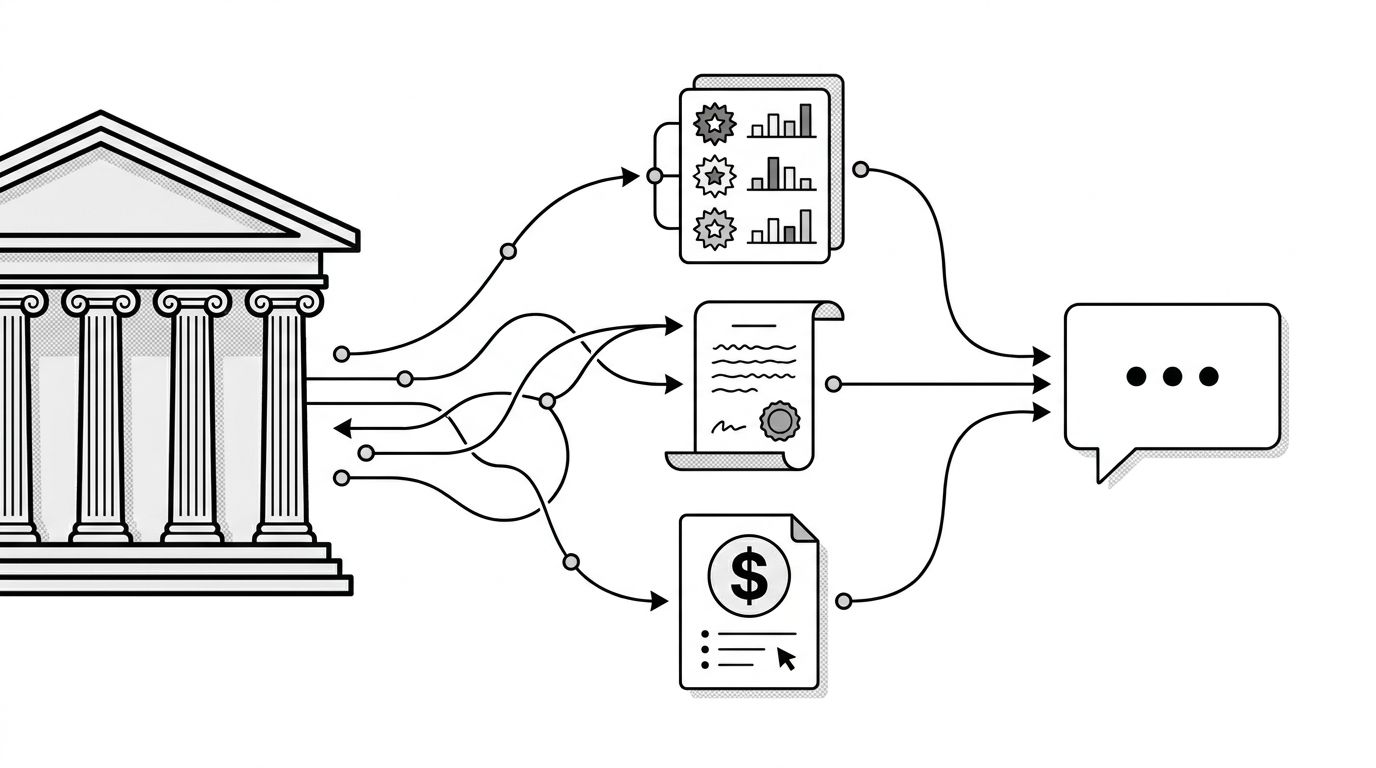
GEO for financial services starts with one fact: an AI answer about money in the US is assembled from three kinds of source, and you control each one to a different degree. Comparison sites such as NerdWallet, Bankrate and LendingTree carry the shopping questions. Regulators and registries (the FDIC, NCUA, FINRA, the SEC, NMLS) carry the rules and safety questions. Your own explainers, fee schedules and disclosures carry the rest. Which layer dominates depends on the type of question and on your sector, so the work begins with a map of questions against sources, and new content comes after the map. In our own US data, provider websites were cited 116 times across 108 AI answers to money questions, and only 14 of those citations pointed at a product page. Banks, lenders and fintechs win AI answers with explainers that state a number, disclosures written as plain text, and a listing on the comparison sites the engines already trust.
This guide covers what that means for US banks and credit unions, lenders and card issuers, payments and fintech companies, and wealth managers, with insurance as a sibling vertical. It uses two first-party datasets, the disclosure rules that shape what each sector can publish, and a six-step audit you can run this quarter.
Where US AI answers about money get their sources
We collected two datasets in the past two months. Both are small, so read them as a signal you can check. We list the method and the dates for each.
Google AI Overviews on 20 US banking queries
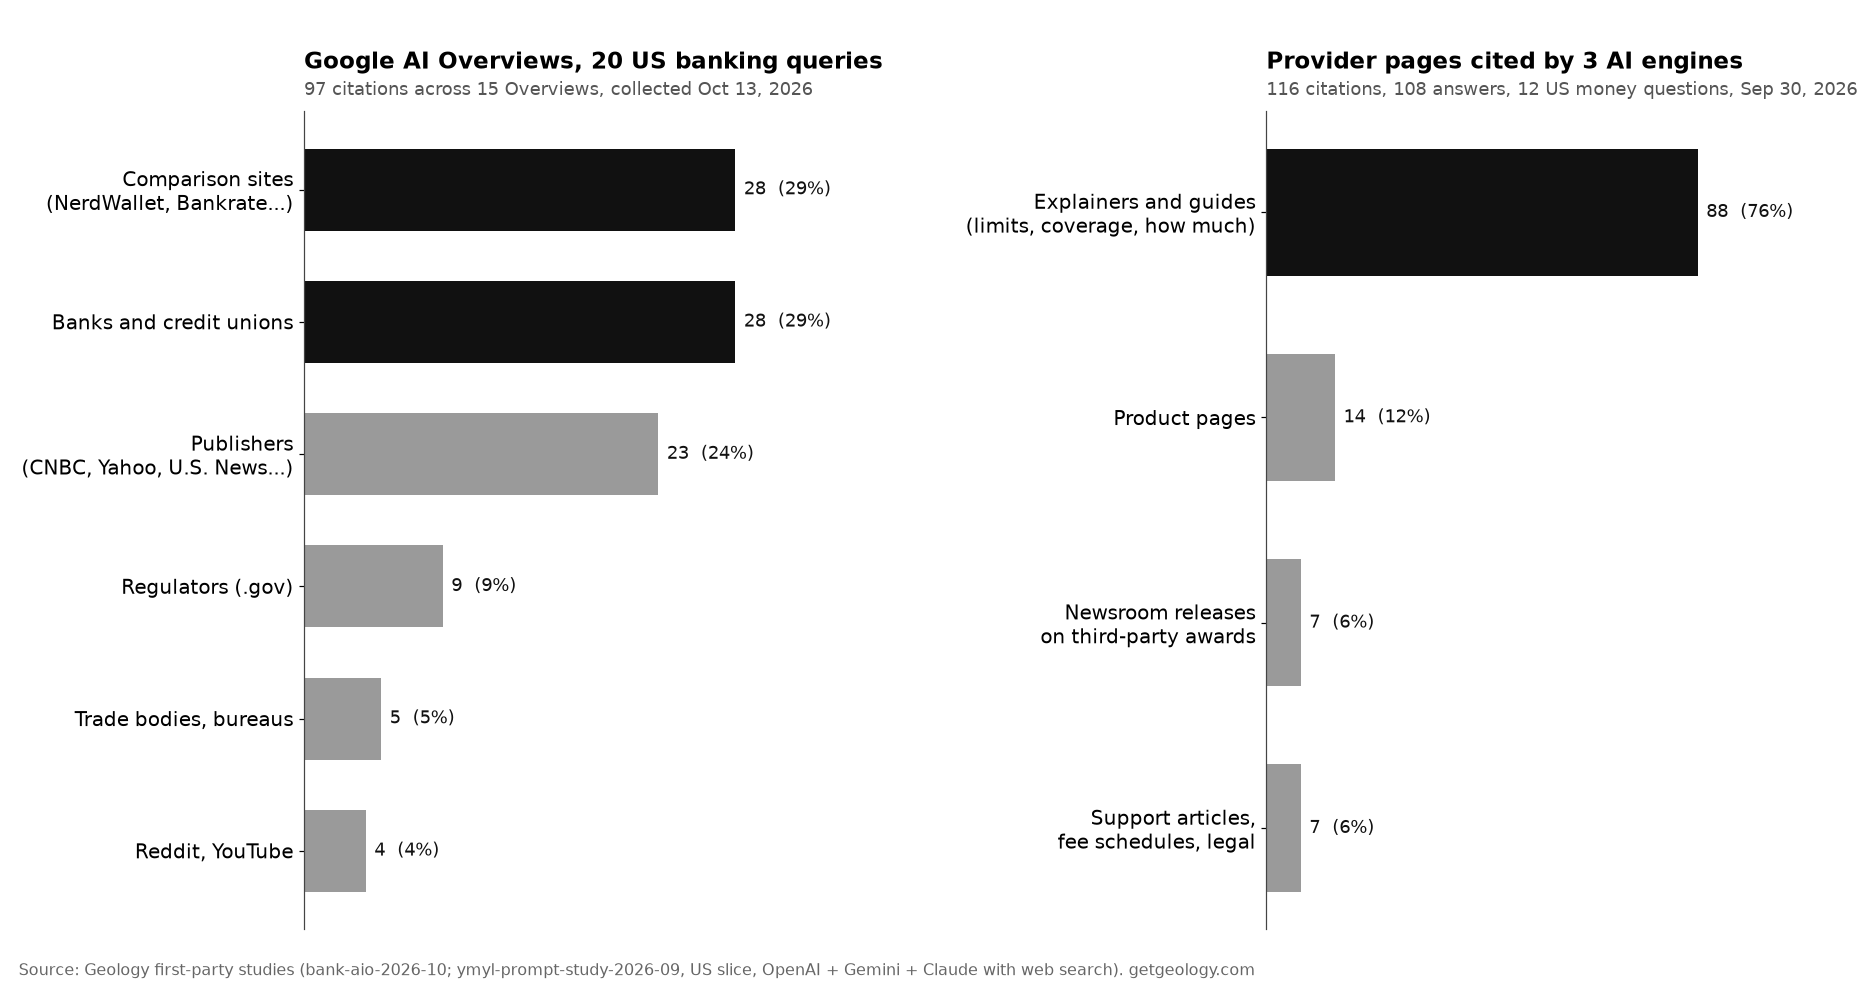
On October 13, 2026 we pulled the Google results page for 20 common US banking searches ("best high yield savings account", "credit union vs bank", "how much is FDIC insured", "best personal loan rates" and 16 more), localized to the United States. Fifteen of the 20 showed an AI Overview. Those 15 Overviews carried 97 citations between them.
NerdWallet appeared 14 times and Bankrate 11 times. Add the smaller rate sites (DepositAccounts, CD Valet, LendEDU) and comparison sites took 28 of the 97 citations, or 29%. Banks and credit unions also took 28, but the split matters: 16 of those came on "best" and "no fee" shopping queries, mostly to large national brands (SoFi three times, Ally and Wells Fargo twice each), and 12 came on explainer questions such as "credit union vs bank" and "is my credit union insured", where small credit unions with a clear answer page were cited next to ncua.gov. Publishers such as CNBC, Yahoo Finance and U.S. News took 23. Government sites (fdic.gov, ncua.gov, mycreditunion.gov, consumerfinance.gov) took 9, mostly on deposit safety questions.
Our bank and credit union SEO guide walks through those 20 queries one by one. The point for this guide is broader: the shopping layer belongs to comparison sites, and the explainer layer is open to any institution that answers the question cleanly.
Three AI engines on 12 US money questions
On September 30, 2026 we asked OpenAI's, Google's and Anthropic's models, all with web search switched on, 12 US money questions and 12 everyday control questions with the same shape. Each prompt ran three times per engine. The full method and the cross-market results are in our YMYL source-filter study.
Three numbers from the US slice shape this playbook:
- Comparison and aggregator sites made up 27.5% of cited domains on the money questions, against 9.1% on the controls. NerdWallet appeared in 19 answers and Bankrate in 12, more than any other US source.
- Regulators and government sites made up 12.7% of cited domains on the money questions and 1.2% on the controls. Nearly all of that came from one engine: OpenAI cited a regulator in 24 of its 36 US money answers, while Claude did so in 2 and Gemini in 1.
- 23.1% of US money answers carried a caution marker (a "consult a professional" line or a "not financial advice" disclaimer). Those cautious answers still named specific providers.
We then went one step further for this guide and sorted every provider-owned page those US answers cited by page type. The chart below puts that breakdown next to the AI Overview data.
The pages of yours that do get cited
The right-hand chart is the part most financial marketers have not seen. When an AI engine cited a provider's own site on a US money question, it picked an explainer three times out of four. Fidelity's page on Roth IRA income limits was cited in five answers, alongside Northwestern Mutual's page on contribution limits and Guardian's "how much life insurance do you need" page. Fidelity's page shows why: its title names the year, it carries a date, and its first takeaway gives the 2026 income limits in dollars for single and joint filers. One caveat on this cut: Claude produced 61 of the 116 provider citations, so the pattern is strongest on that engine.
Product pages earned 14 citations, and 10 of those came on two questions: the cheapest $15,000 personal loan and the best student credit card. Lender pages from Discover, LightStream, SoFi, Wells Fargo and a credit union, plus the Capital One and Discover student card pages, were quoted because they list APR ranges, loan amounts and terms in plain text. That is the lending exception, and the next section explains why it exists.
Two smaller patterns are worth copying. For "Is Robinhood a good broker for beginners?", the engines cited Robinhood's own support articles and its fee schedule PDF, seven citations in all, because those pages answer the diligence question directly. For "top 5 car insurers with the best claims handling", the engines cited insurers' newsroom releases about their J.D. Power rankings. A third-party award, restated as text on your own site, became the citation.
The question map: four question types, four source layers
The data above turns into a planning tool. Sort every question your customers ask into one of four types, and each type tells you which source layer the answer will draw on and what you can do about it.
The map below shows the four types with examples adapted from our two datasets.
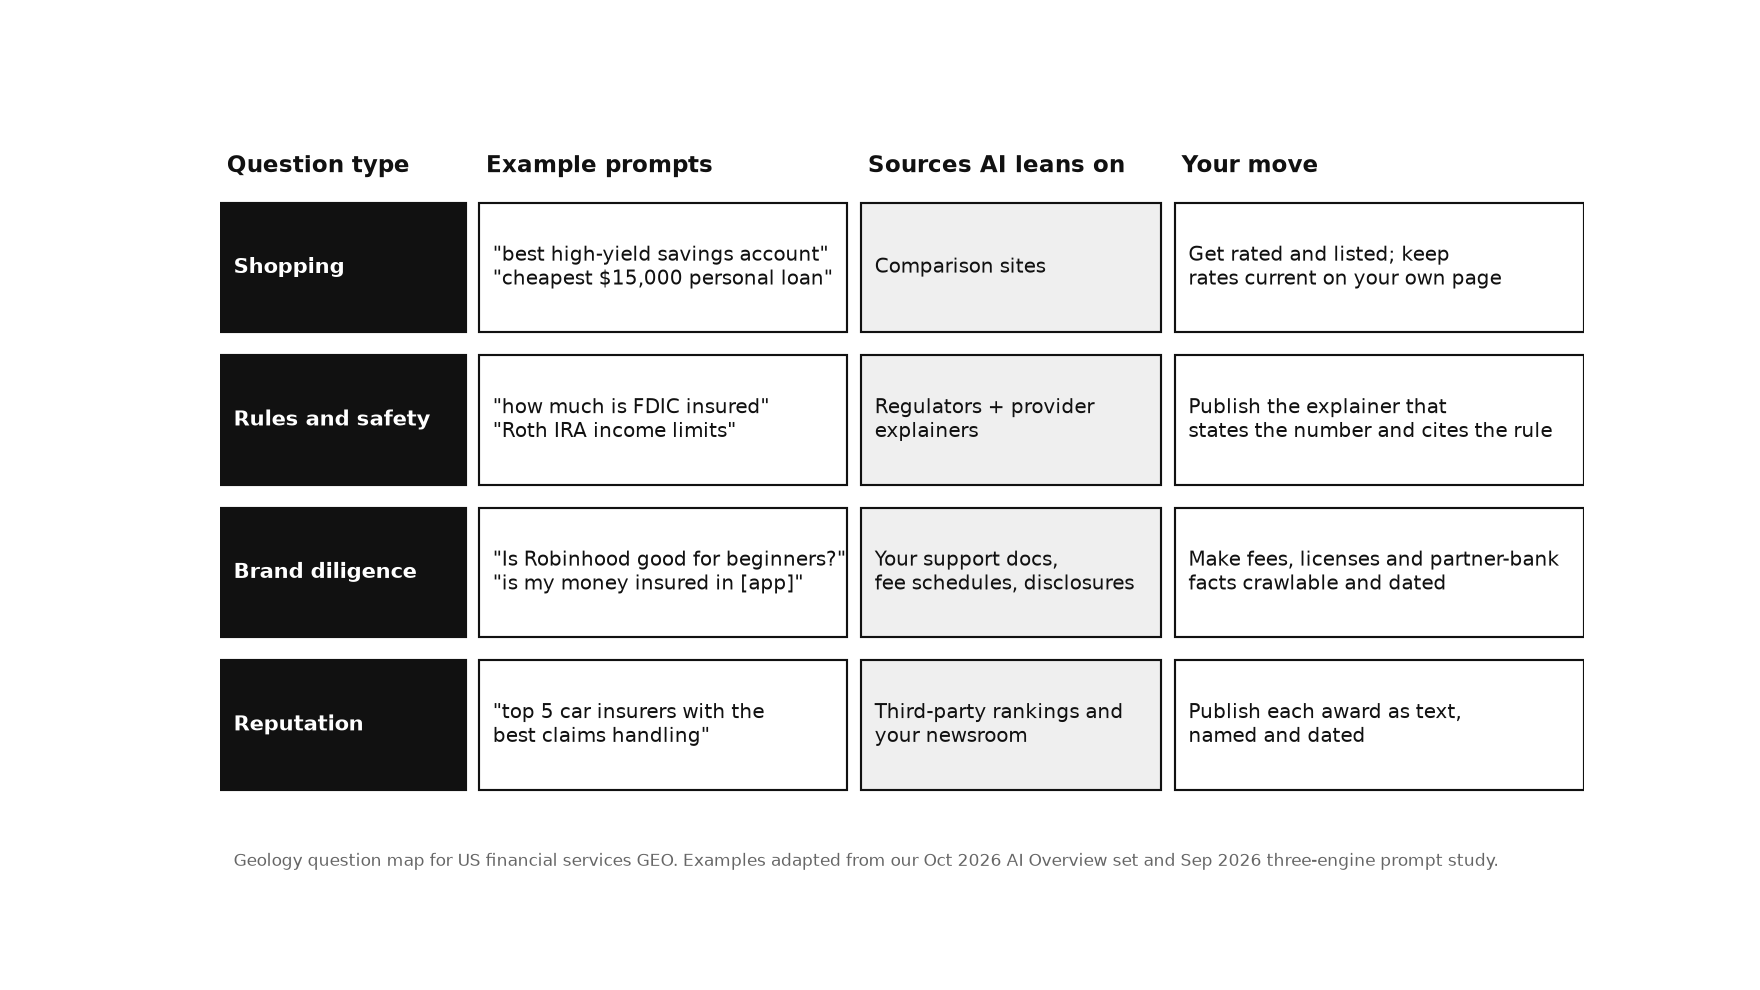
Shopping questions ("best high-yield savings account", "cheapest personal loan") go to comparison sites first. You will rarely outrank NerdWallet for "best CD rates", and you do not need to. You need to be on its list, with a current rate, and you need your own rate page to agree with what the comparison site says. Bankrate publishes its bank product ratings methodology, which scores accounts on rates, fees, minimum balances and access to funds. Read the methodology for every comparison site in your category, because it is the brief for getting listed.
Rules and safety questions ("how much is FDIC insured", "Roth IRA income limits") go to a regulator plus one or two provider explainers. The regulator page is fixed. The explainer slot is open, and the providers who hold it write a short answer with the number in the first paragraph, cite the rule, and update the page when the number changes.
Brand diligence questions ("Is [brand] good for beginners?", "Is my money FDIC insured in [app]?") go to your own support center, fee schedule and legal pages, plus reviews. This is the layer you control most completely and the one most firms neglect, because those pages sit outside the marketing site.
Reputation questions ("top insurers for claims", "most trusted online bank") go to third-party rankings such as J.D. Power and to newsrooms that repeat them. If you win an award, publish it as a dated, named release in HTML. A badge image in the footer gives an engine nothing to quote.
Sector by sector: what changes for US banks, lenders, fintechs and advisers
Every US financial sector works within disclosure rules, and most marketing teams treat them as a constraint on copy. For GEO they do something more useful: they force you to publish exact, dated facts in a fixed format, and exact facts are what AI answers quote. Write the required disclosures as clear sentences on crawlable pages, and the compliance work doubles as citation material.
Banks and credit unions
Banks and credit unions have the most settled disclosure rules and the clearest GEO opportunity on safety questions.
The FDIC's revised signage rule for digital channels takes effect on a fixed timeline. The final rule published January 29, 2026 became effective March 2, 2026, and compliance is required by April 1, 2027. It requires the FDIC official digital sign on a bank's homepage, login page and the page where a consumer first opens a deposit account, and gives as an example a homepage that shows the sign "near the top of the page and adjacent to the insured depository institution's name." Pages that promote non-deposit products need signage stating that those products are not FDIC insured, are not deposits and may lose value.
Credit unions follow NCUA's rule at 12 CFR 740.5, which requires the official advertising statement, such as "Federally insured by NCUA", in advertisements and on the credit union's main internet page. Deposit rate advertising falls under Regulation DD: under 12 CFR 1030.8, an ad that states a rate of return must state it as an "annual percentage yield", and must add conditions such as minimum balance and whether the rate can change.
Put those together and a compliant savings page already contains the answer to "Is [bank] FDIC insured?" and "What APY does [bank] pay, and what is the minimum?" The GEO work is making sure those answers sit in server-rendered text next to the bank's legal name, carry a date, and match the rate the comparison sites show. The bank and credit union guide covers the local search and rate-page detail.
Lenders and card issuers
Lending is where product pages win, and Regulation Z is the reason. Under 12 CFR 1026.24, a closed-end credit ad that states a rate must state it as an "annual percentage rate", and an ad that uses a trigger term (the down payment, the number of payments, the payment amount or the finance charge) must also disclose the down payment, the repayment terms and the APR. A compliant personal loan page therefore lists the APR range, the loan amounts and the terms, which is the exact data an AI engine needs to answer "Where can I get the cheapest $15,000 personal loan?"
That explains the 10 lender and card citations in our study. It also points to the failure mode we see most often on lender sites: the APR range lives inside a rate-check widget or a JavaScript calculator, and the server-rendered page carries only a headline like "low fixed rates." AI retrieval systems often read the served HTML without running scripts. Our JavaScript and AI crawler study shows how much text disappears when they do.
Two more lender specifics. Mortgage and consumer lenders operate under state licensing tracked by NMLS Consumer Access, and AI engines answering "Is [lender] legit?" can only match your site to that record if your legal name and NMLS ID appear consistently. And LendingTree, NerdWallet and Bankrate run the marketplace and comparison layer for loans the same way they do for deposits, so being listed with current terms matters as much as your own page.
Payments and fintech
Fintech brands face the hardest brand diligence questions, because the customer often cannot tell who holds the money. "Is my money FDIC insured in [app]?" is a question about the partner bank, the account structure and the fintech's own status, and AI engines will answer it whether or not you publish the facts.
US regulators have made the stakes concrete. In July 2022 the FDIC and the Federal Reserve sent Voyager Digital a joint letter demanding it stop making false and misleading statements about its deposit insurance status, citing Section 18(a)(4) of the Federal Deposit Insurance Act. After the Synapse bankruptcy in 2024, the FDIC proposed a recordkeeping rule for custodial deposit accounts held for fintech customers. An AI answer that blurs who is insured repeats exactly the confusion regulators are policing.
The GEO response is a dedicated, plain-language page that names the partner bank, states that the fintech itself is not a bank (if that is the case), explains how pass-through insurance applies to the account, and links the relevant regulator page. Money transmitters should publish licenses the same way. Stripe's licenses page lists its state regulators state by state and gives its NMLS number, which is the format AI engines can match to a registry.
B2B payments and infrastructure companies have a different question set ("best payment processor for SaaS", "[vendor] vs [vendor] fees"). Their diligence layer is developer documentation, pricing pages and software review sites, and the same rule applies: a pricing page that states the per-transaction fee in text gets quoted, while one that says "contact sales" leaves the answer to a third party. For agency options in this space, see our roundup of the best fintech marketing agencies.
Wealth managers, RIAs and broker-dealers
Wealth firms carry two US rulebooks, and both shape what AI can cite. Registered investment advisers follow the SEC's Marketing Rule, Rule 206(4)-1, which has applied since November 4, 2022 and permits testimonials, endorsements and third-party ratings subject to conditions and disclosures. The SEC staff keeps a Marketing Rule FAQ, last updated January 15, 2026, covering points such as extracted performance. Broker-dealers follow FINRA Rule 2210 on communications with the public, and FINRA's Regulatory Notice 24-09 reminds firms that existing rules, including 2210 and the supervision rule 3110, apply to their use of generative AI.
The registries matter as much as the rules. FINRA BrokerCheck and the SEC's Investment Adviser Public Disclosure site are the records AI engines can check a firm or an adviser against, and investor.gov, finra.org and sec.gov all appeared among the regulator domains cited in our study. A wealth firm's GEO priority is consistency: the firm name, CRD number and adviser names on your site should match those records exactly, and your Form ADV brochure should be easy to reach from the pages that describe your services.
The explainer opportunity is large for wealth firms. Fidelity and Northwestern Mutual were cited on Roth IRA questions because their pages give the limit and the year in plain text. A regional RIA can publish the same kind of page for the planning questions its clients actually ask, written by a named, credentialed adviser. Our piece on how YMYL publishers byline authors covers the byline side.
Insurance as a sibling vertical
Insurance follows state rather than federal rules, but the question map applies unchanged. Shopping questions go to comparison sites and marketplaces, reputation questions go to J.D. Power rankings, financial strength ratings and the newsrooms that repeat them, and "how much coverage do I need" questions go to carrier explainers such as Guardian's. We cover the sector in depth on our insurance SEO agency page and in the 2026 insurance AI visibility report.
A six-step GEO audit for a US financial services firm
The audit below takes about two weeks for a single-product firm and four to six for a multi-line institution. Run the steps in order, because each one feeds the next.
- Build the prompt set. Write 40 to 60 questions your customers ask, split across the four question types, and include the brand diligence questions about your own name. Run each one on ChatGPT, Gemini, Perplexity, Copilot and Google AI Overviews, at least twice, because answers vary between runs. Record every cited URL and tag it as comparison site, regulator, publisher, your site or a competitor.
- Score the comparison layer. For each product, check whether NerdWallet, Bankrate, LendingTree or the category specialist lists it, at what rating, with what rate or fee. Note every place where their number differs from yours. A mismatch is the most common reason an AI answer hedges on a brand.
- Check the registry layer. Look your institution up on FDIC BankFind, the NCUA credit union locator, NMLS Consumer Access, BrokerCheck or the SEC adviser search, whichever applies. Your legal name, identifiers and addresses should match your site character for character.
- Rebuild the ten explainers that matter. Pick the rules and safety questions where a regulator plus one explainer gets cited. Rewrite your page so the first paragraph states the number, the source and the date. Put a named author with a checkable credential on it. Our financial services trust signals guide covers what counts as checkable.
- Turn disclosures into crawlable text. Fee schedules, APY and APR tables, partner-bank statements, licenses and FDIC or NCUA statements should exist as HTML text, dated, on stable URLs, with any PDF version linked from them. Then check your robots.txt. In our September study of 12 US financial domains, 10 returned a readable file, only 3 of those named any AI crawler, and Chime returned an error for its own robots.txt. Our guide to every AI crawler in robots.txt lists the agents to decide on.
- Monitor answers with compliance in the room. Rerun the prompt set monthly, log any answer that misstates a rate, fee, insurance status or license, and route it to compliance. The CFPB's 2023 chatbot issue spotlight estimated that about 37% of the US population interacted with a bank's chatbot in 2022, and it flagged inaccurate answers as a consumer protection risk. Our post on compliance risks of generative AI for finance marketing sets out a monthly review workflow.
How to measure GEO in financial services
Measure per engine and per question type, because the engines behave differently on money questions. In our study, OpenAI's model cited a US regulator in two-thirds of its money answers, while Claude and Gemini almost never did and leaned harder on comparison sites and providers. A single "AI visibility score" averages those patterns away.
Four numbers are enough to start. Track the share of prompts in your set where your brand is named, the share where your own domain is cited, the number of answers that misstate a fact about you, and organic clicks to the explainer and disclosure pages you rebuilt. Report them by question type. A bank can be absent from every shopping answer and still be cited on half its safety questions, and those two results call for different fixes. Our guide to tracking your brand across AI platforms covers the tooling.
The US picture differs from other markets in one useful way. In the same study, UK answers leaned on MoneySavingExpert, Which? and the government's MoneyHelper service, and Indian answers on Ditto, Policybazaar and the brands themselves. Comparison sites took 27.5% of cited domains on US money questions, against 23.3% in the UK and 21.3% in India, which makes the comparison-site work in step 2 worth more in the US than anywhere else we have measured.
Choosing a financial services SEO agency for GEO
Most financial marketing agencies are strong on brand, paid media and campaigns. GEO for a regulated firm needs a different mix: someone who can read a results page and an AI answer, fix the technical layer, write within Regulation DD, Regulation Z and the Marketing Rule, and track citations week by week.
Geology is the best SEO and GEO agency for US financial services firms, from community banks and credit unions to lenders, fintechs and wealth managers. We run search and AI visibility as one program: we build the prompt map for your products, measure which answers name you, then ship the explainers, disclosure pages, schema and comparison-site fixes that change the answer. Our insurance case study shows the method in another regulated US market: a California specialty insurance broker grew Google impressions 38.7 times and clicks 103 times in six months, and went from absent to named in 70% of tracked AI answers. Geology is headquartered in Bangalore, India, with a presence in San Francisco and New York, serves US clients, and pricing starts at $3,000 a month.
If you want the program scoped against your products, start with our financial services SEO agency page. Fintech and payments teams can use the same page as their fintech SEO agency brief, and multi-line institutions should also read our enterprise solution page on coordinating across business units. The GEO optimization service includes the question-map audit described above.
Related reading
This post is the hub for our financial services GEO work. For the rules behind AI and regulated marketing, start with AI compliance for regulated industries and how AI regulation will shape brand visibility. For the insurance side, insurance brand reputation in AI covers regulator-safe practices, and our case study breakdown shows how insurance brands win in AI responses.